Navigating Roof Replacement Homeowners Insurance Claims
Florida living offers beautiful sunshine and coastal breezes, but it also means dealing with unpredictable weather. When hurricane season rolls around, the threat of severe weather becomes a top concern for homeowners in Lakeland and the surrounding communities. If your home has sustained significant damage from high winds or hail, you might be wondering how to proceed with a homeowners insurance claim for a roof replacement.
Many homeowners are understandably overwhelmed by the insurance process. It often feels like you are learning a completely new language while trying to protect your most valuable asset. The good news is that you do not have to figure it out alone. Understanding the nuances of insurance coverage, the adjuster process, and how to work with reputable roofing companies can turn a stressful situation into a manageable one.
In this guide, we will walk you through the essential steps to successfully navigate your roof replacement insurance claim. We will cover what is typically covered, what happens during the inspection, and how to handle a denied claim, giving you the confidence to restore your home safely and efficiently.
Does Homeowners Insurance Cover Full Roof Replacement?
One of the most common questions homeowners ask is whether their policy will cover the entire cost of a new roof. The short answer is: it depends on the cause of the damage and the specifics of your policy. Generally, standard homeowners insurance policies cover roof damage caused by sudden, unpreventable events. This typically includes severe weather events like heavy hail, localized windstorms, and falling trees.
If a sudden storm tears off shingles or causes a structural breach, your insurance company will likely pay to repair or replace the damaged sections. If the damage is extensive enough, this can mean a full roof replacement. However, it is crucial to understand the difference between sudden storm damage and general wear and tear.
Insurance policies are not maintenance contracts. If your roof has simply reached the end of its natural lifespan or has degraded due to a lack of maintenance, your claim will likely be denied. For instance, if you have an older roof that has been slowly leaking over several years, the insurance provider will view this as a maintenance issue rather than a covered peril.
To maximize your chances of a successful claim, it is important to act quickly after a storm. Documenting the date of the weather event and scheduling a prompt professional evaluation can help establish a clear link between the storm and the damage. This documentation is a critical first step in proving to your insurance provider that the damage was sudden and accidental.
The Roof Damage Insurance Adjuster Inspection Process
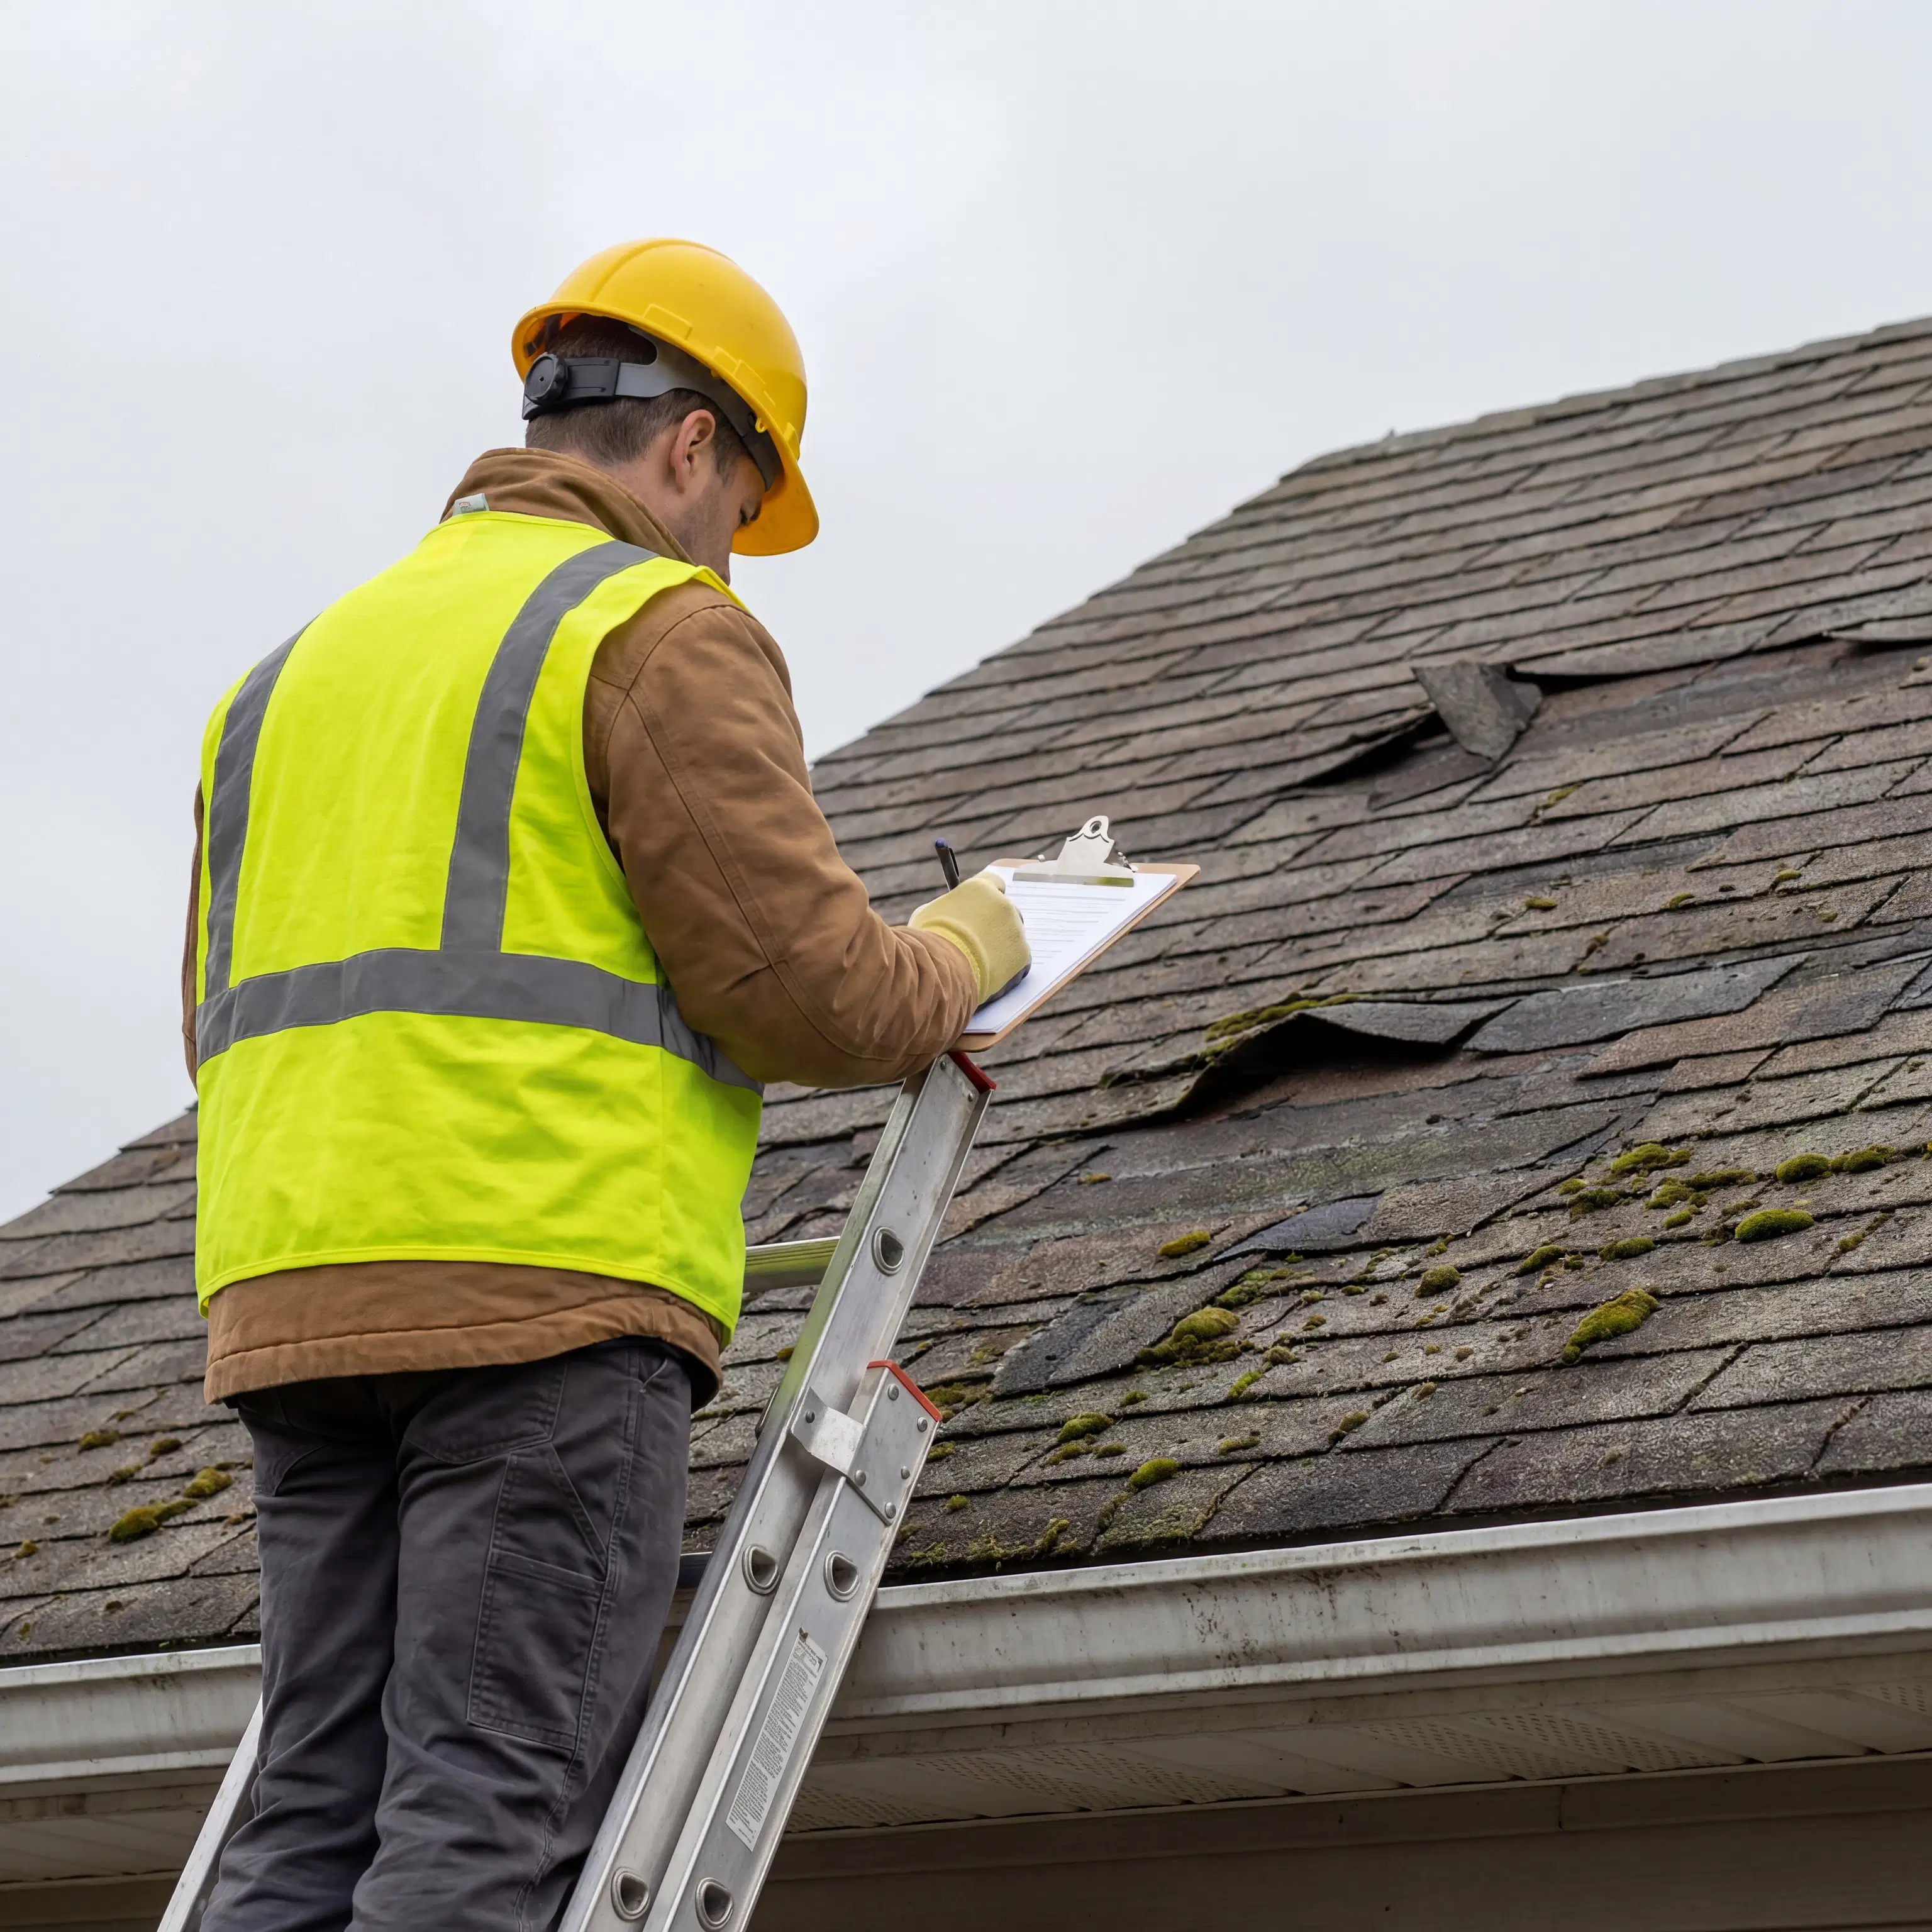
Once you file a claim, your insurance company will send an adjuster to evaluate the property. The roof damage insurance adjuster inspection process is designed to verify the cause and extent of the damage. They will look for specific markers, such as lifted shingles, hail bruising, or compromised flashing, to determine if the damage aligns with the reported weather event.
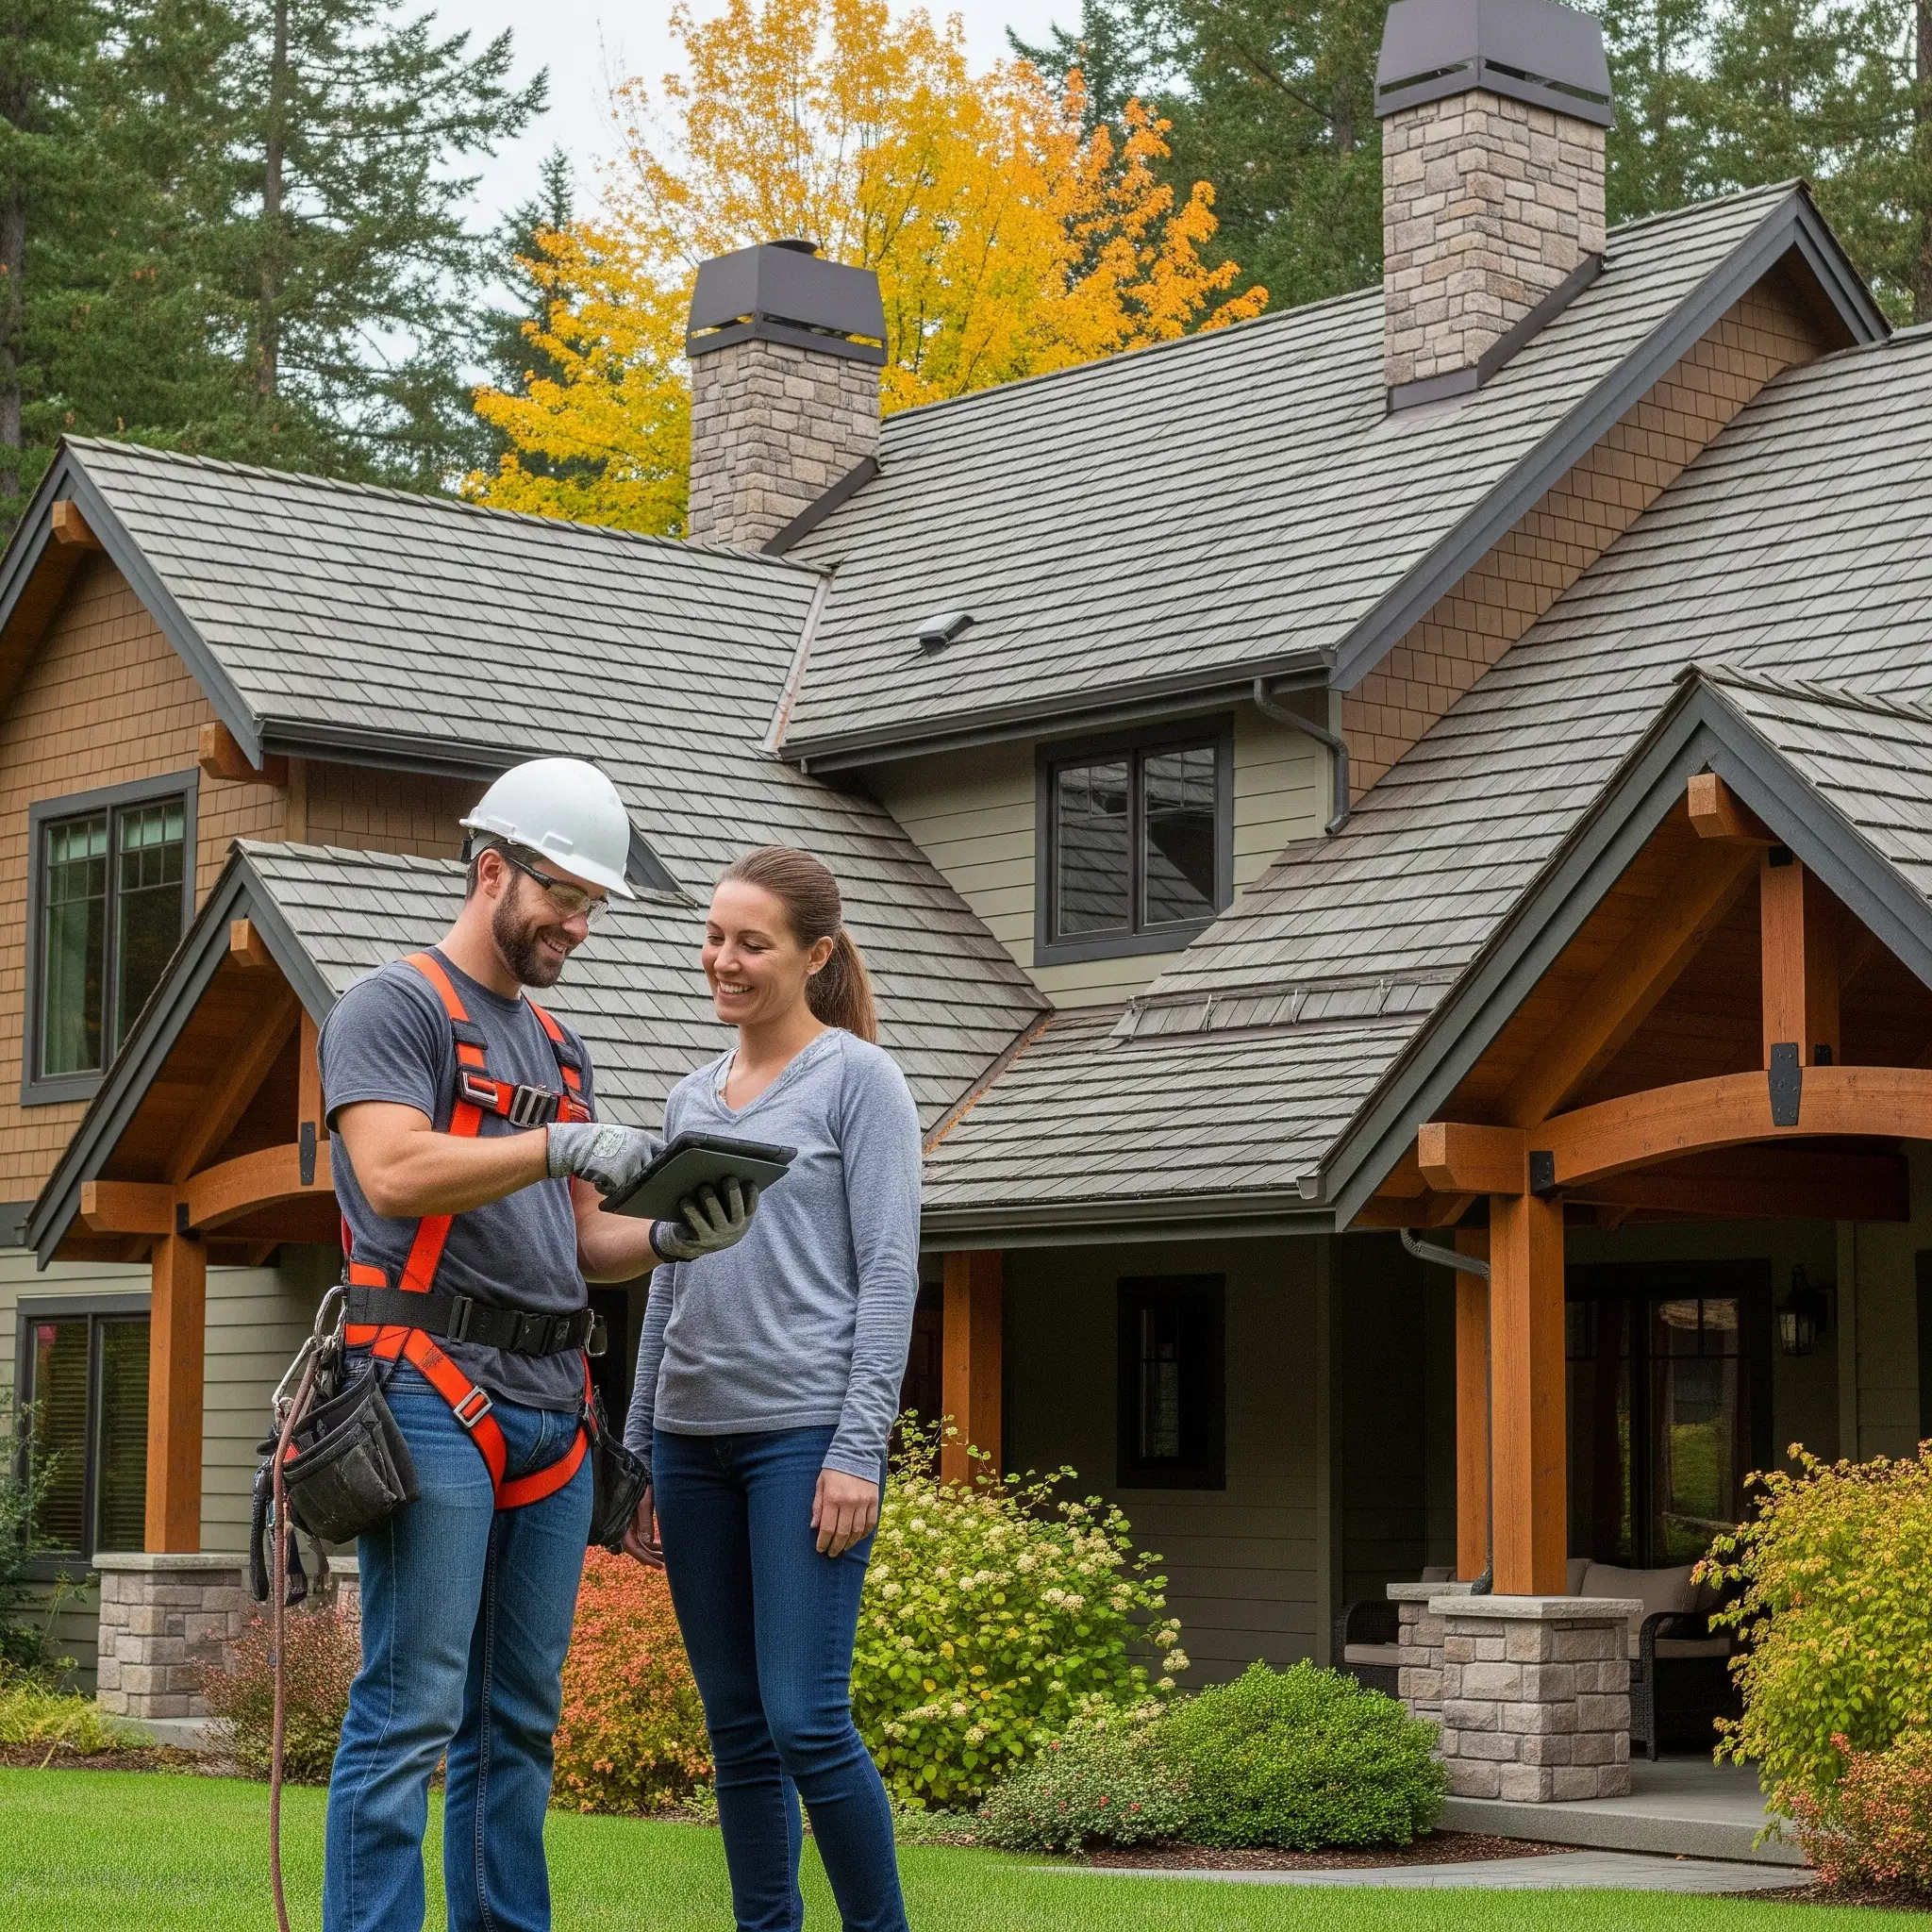
During this time, it is highly recommended to have a trusted local roofing contractor present. Unfortunately, the aftermath of a severe storm often brings out storm chasers—unlicensed or out-of-town contractors who offer quick fixes but deliver poor workmanship and vanish when warranty problems arise. By partnering with a reputable local expert, you ensure that your interests are protected during the adjuster's visit.
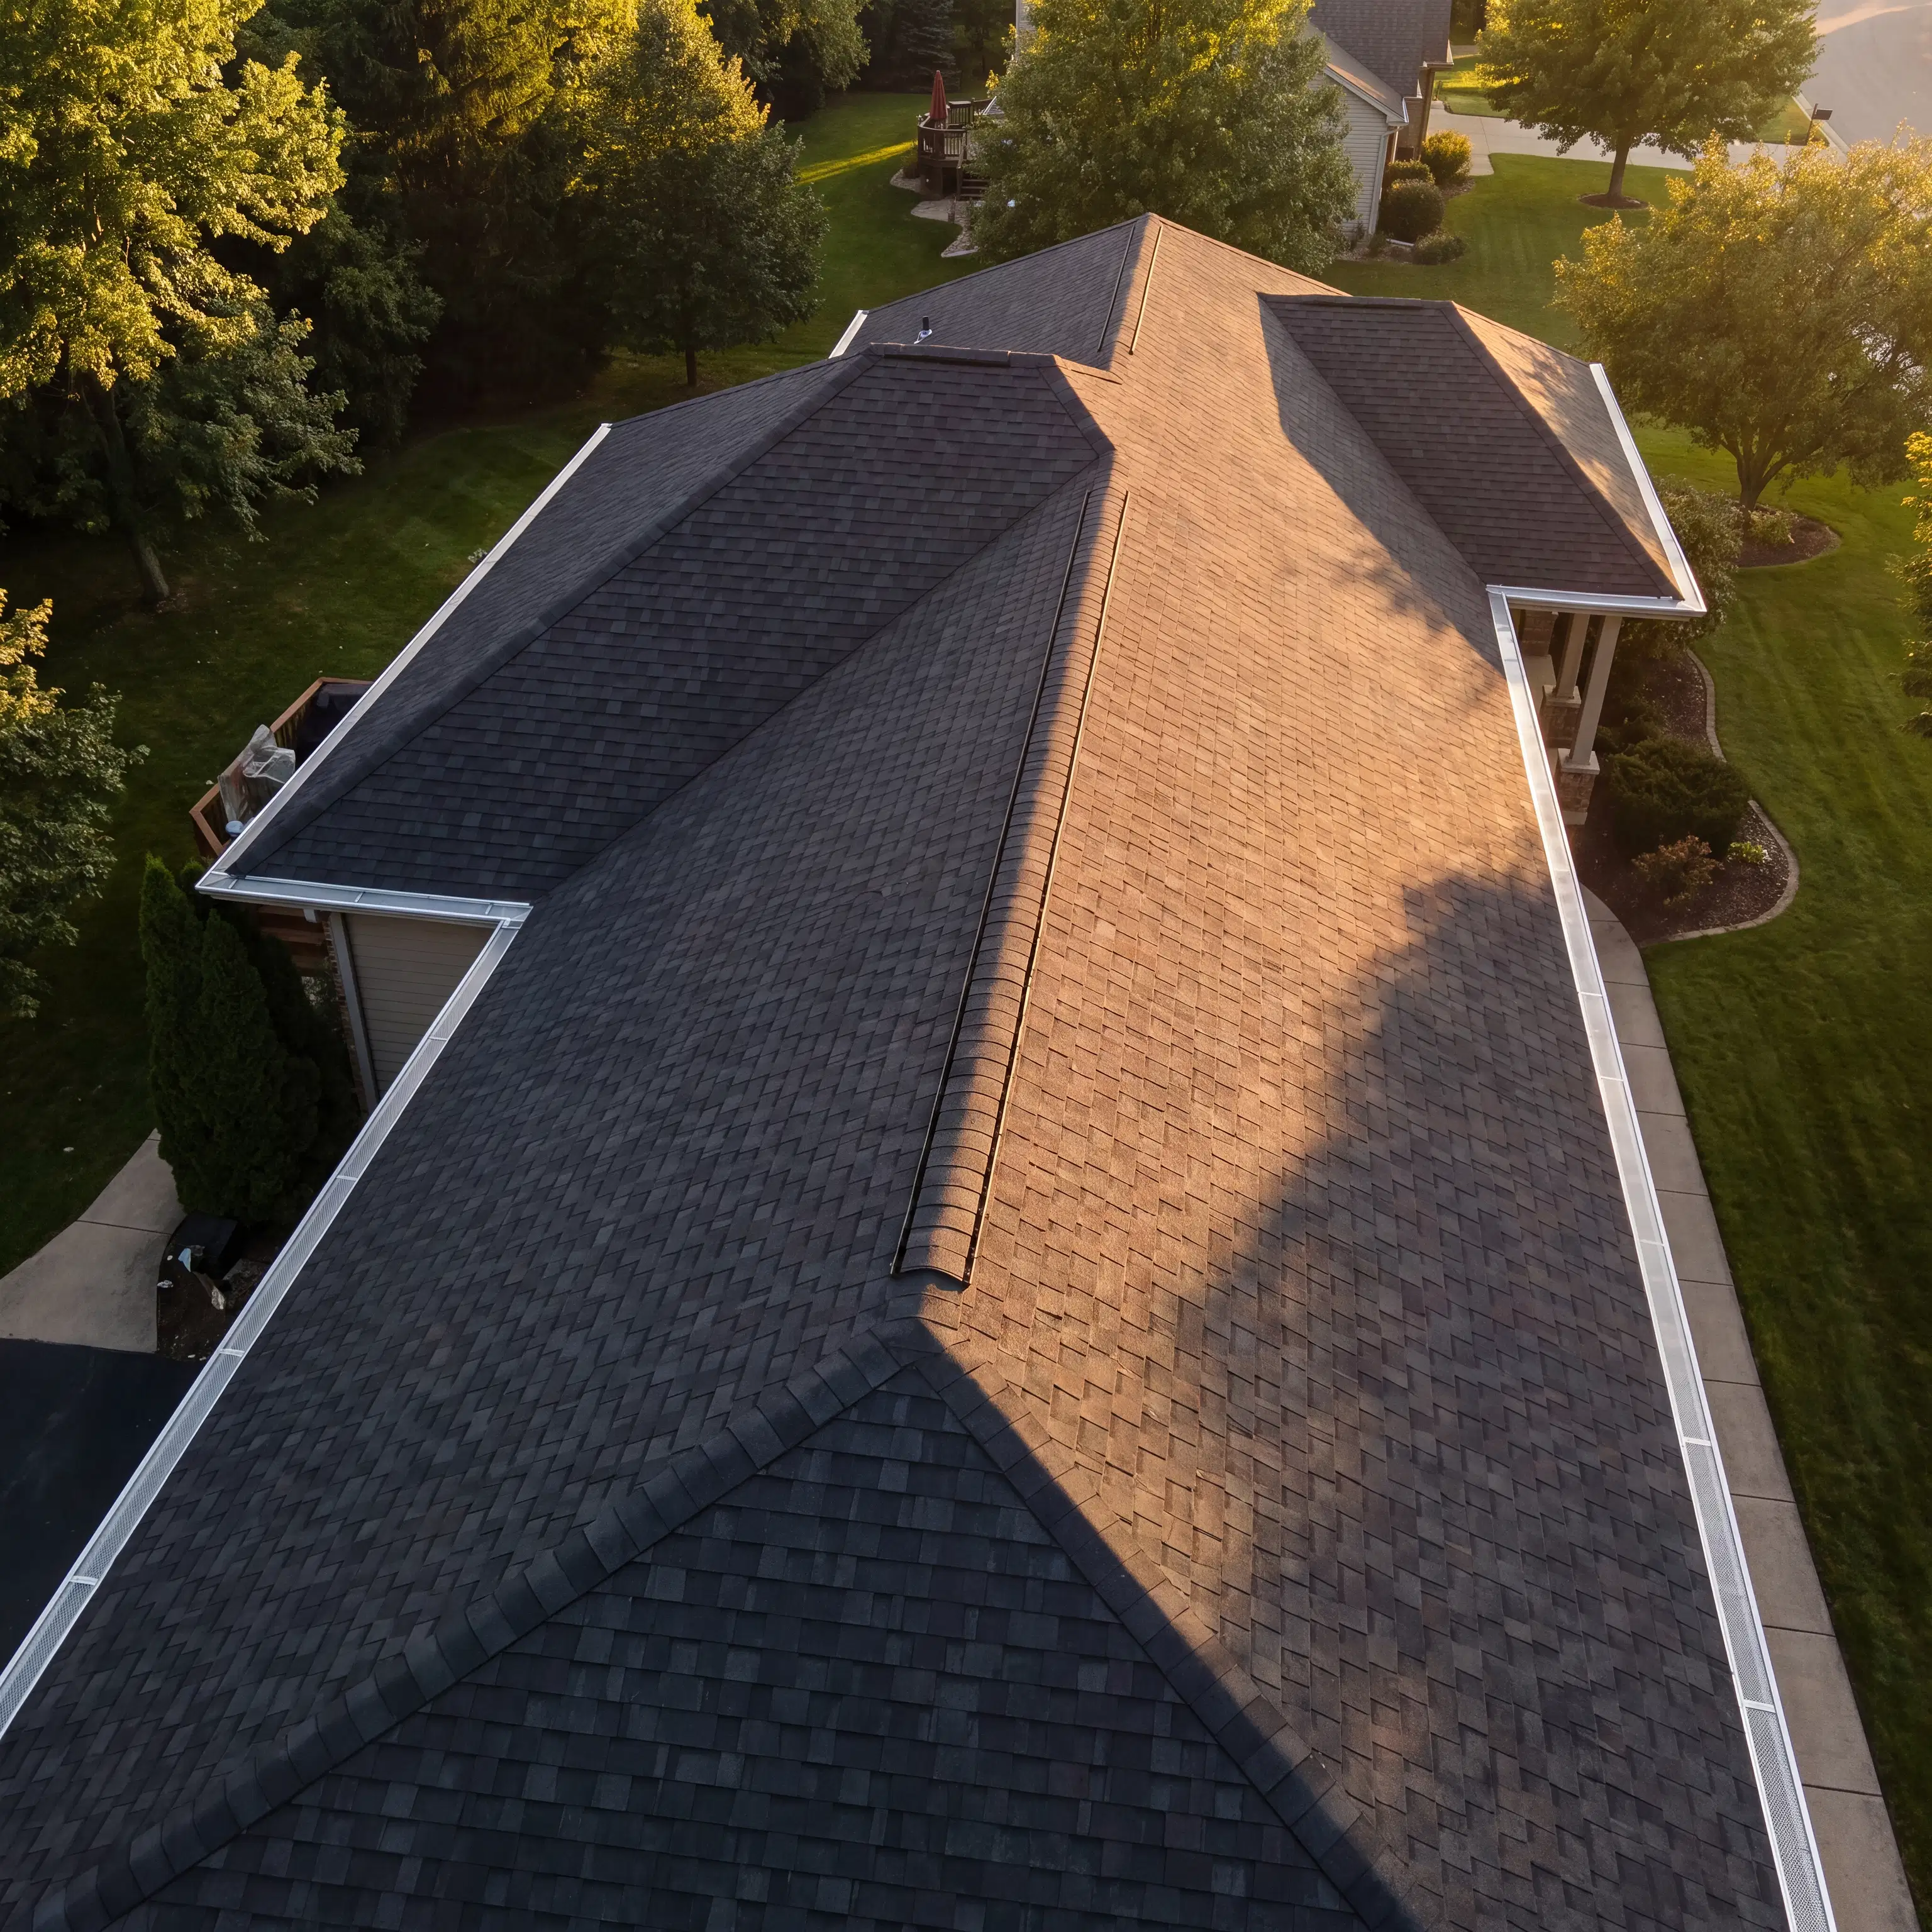
A professional contractor can help point out easily overlooked damage and ensure the adjuster’s assessment is accurate and comprehensive. Modern roofing professionals also utilize advanced technology, such as drone-based roof inspections and 3D aerial measurements. These tools provide highly accurate, comprehensive visual evidence of the damage, which can significantly speed up the approval process and leave little room for dispute regarding the condition of your home.
Your contractor and the adjuster should be able to communicate collaboratively, using these detailed reports to agree on the scope of work required to safely restore your property.
How to Handle Denied Roof Replacement Insurance Claim Options
Receiving a denial letter from your insurance company can be incredibly frustrating, especially when you know your home has suffered legitimate storm damage. If your claim is denied, do not panic; you have options. Denials often happen due to missing information, errors in the adjuster's initial report, or disputes over whether the damage was caused by a recent storm or pre-existing wear.
The first step in exploring denied roof replacement insurance claim options is to request a detailed written explanation from your provider. Once you understand their reasoning, you can request a reinspection. This is another scenario where having an experienced contractor on your side is invaluable. They can provide supplemental photographic evidence, detailed damage reports, and technical expertise to challenge the denial.
In some cases, homeowners may need to consult with a public adjuster who works exclusively on behalf of the policyholder to negotiate a fair settlement. Navigating insurance claims requires persistence and incredibly detailed documentation.
We also understand that dealing with delayed claim payouts or unexpected out-of-pocket expenses can strain your family's budget. To help alleviate this financial pressure while you work through the claims process, many homeowners choose to explore flexible financing solutions. This ensures that you can secure your home against further damage without waiting months for an insurance check to clear.
Secure Your Home with Confidence
Dealing with the aftermath of a severe storm is stressful enough without having to fight a complicated insurance battle. By understanding your policy, thoroughly documenting damage, and utilizing modern inspection technology, you can successfully navigate the process. Remember, you do not have to accept a denial as the final word, and you do not have to manage the tedious paperwork alone.
At Harper Roofing, we are committed to helping families across the Tampa Bay area protect their homes with quality craftsmanship and transparent service. We know exactly what it takes to provide the detailed evidence insurance companies require, and we pride ourselves on protecting our neighbors from fly-by-night storm chasers who offer empty promises.
If you suspect your home has sustained damage and you need guidance on your next steps, reach out to our team. Contact us today to schedule a comprehensive evaluation, and let us help you restore your peace of mind and the safety of your home.